All Categories
Featured

Securing Coverage to Support Families
Table of Contents
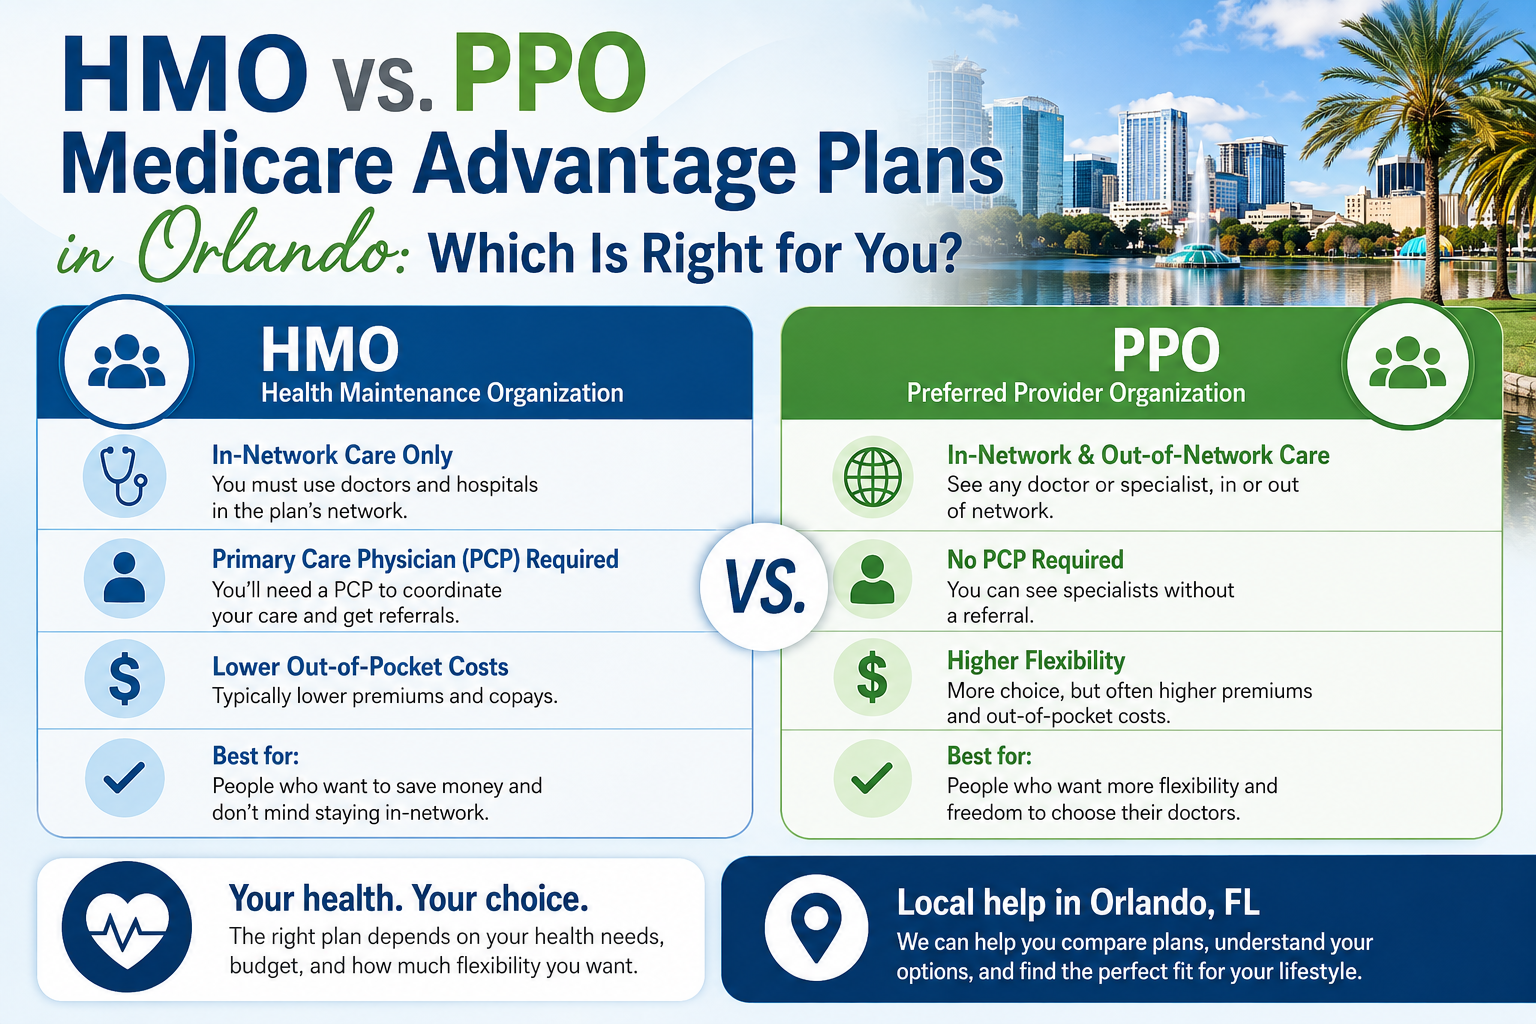
Like all health plans, receiving in-network care is best to keep your out-of-pocket costs low. However, unlike HMO strategies that won't cover any portion of your costs if you look for out-of-network care (other than in a covered emergency situation), you can get out-of-network care when taking a trip out of your regular plan network location with a PPO policy.
Common Annuity MythsCost-conscious people ought to consider a couple of drawbacks to PPO prepares that may make getting care more pricey. While they're versatile and convenient, PPO strategies have greater premiums. According to KFF, PPO plans had the greatest yearly premiums compared to HMOs and point-of-service strategies (POS) in 2023. You'll likewise have to pay more expensive medical expenses if you receive care from an out-of-network provider.
If you do have a deductible, it's likely to be more expensive than other plan types. While your insurer will share the expense with you, you'll likely pay a higher coinsurance portion for out-of-network providers. When you visit an in-network company, they'll submit your claim to your medical insurance business in your place.
PPO insurance policy holders may find the claim filing procedure complicated if they're not utilized to it or lengthy if they often need out-of-network care from an expert. In 2023, the typical annual premium for a group PPO strategy was $8,906 for self-only protection and $25,228 for family coverage2. Companies contributed $7,399 towards a self-only strategy, and employees contributed $1,507.
Analyzing PPO Network Flexibility versus Monthly Costs
The average deductible for PPO plans was $1,281. As pointed out above, PPO prepares bought on the ACA marketplaces also have a maximum out-of-pocket limit of $9,450 for self-only protection and $18,900 for family strategies. To summarize how HMO and PPO plans differ, have a look at our quick chart. Self-only coverage: $8,203 Family protection: $23,758 Self-only protection: $8,906 Household protection: $25,228 For 2024 ACA market plans, the maximum limitation is $9,450 for self-only coverage and $18,900 for family protection.

Yes No Yes No Some plans do. A lot of strategies do. Yes. If they do, they're accountable for paying the entire bill on their own unless the care was for an emergency situation. Yes. However, individuals might have a higher coinsurance or medical costs. Whether you have an HMO or PPO strategy, you can utilize a health repayment arrangement (HRA) to lower out-of-pocket medical expenses.
Common Annuity MythsOnly companies can launch and contribute towards an HRA. Companies utilize an HRA to give their employees a month-to-month allowance to pay for medical costs. When an employee purchases an eligible item or service, they send documents revealing evidence of purchase, and their company reimburses them approximately their allowance quantity.
Securing Coverage for Families
(MEC). (ICHRA): An ICHRA is also a stand-alone HRA, however it's offered to employers of all sizes and has no contribution limitations.
But, they must have a qualifying form of private health coverage to take part. Companies can set various allowances based on staff member classes for included modification. Group protection HRA (GCHRA): Also known as an integrated HRA, a GCHRA is for employers of any size who provide a group health strategy. Just employees registered in their company's group plan can get involved.
While they have no optimum contribution limitations, the IRS does not permit repayments for month-to-month premiums. No matter whether it's utilized in coordination with an HMO or PPO plan, there's an HRA that can help staff members pay for their out-of-pocket medical expenses and, in some cases, their medical insurance premiums. An HRA is a popular alternative choice over conventional health advantages since they're budget-friendly for companies and flexible enough for each staff member.
Why Whole Life Builds Future Wealth
An HMO might be your best bet if you're looking for a plan with a low premium. However, a PPO plan supplies extra versatility if you require more control over your healthcare. That's why looking into these plans thoroughly, including their pros, cons, and average expenses, is the very best primary step you can take in the past deciding.
Worker compensations will be tax-free if their specific health plan offers minimum essential protection (MEC). Employers can repay staff members for out-of-pocket expenses and health insurance coverage premiums, consisting of those for an HMO or PPO plan. Specific protection HRA (ICHRA): An ICHRA is likewise a stand-alone HRA, but it's available to employers of all sizes and has no contribution limits.
But, they need to have a qualifying type of specific health coverage to get involved. Employers can set different allowances based on staff member classes for included modification. Group protection HRA (GCHRA): Also called an incorporated HRA, a GCHRA is for companies of any size who use a group health strategy. Just employees registered in their company's group strategy can take part.
Comparing PPO vs HMO Insurance
While they have no optimum contribution limitations, the IRS does not permit repayments for regular monthly premiums. No matter whether it's used in coordination with an HMO or PPO strategy, there's an HRA that can assist staff members pay for their out-of-pocket medical costs and, often, their health insurance coverage premiums. An HRA is a popular alternative option over standard health advantages because they're budget-friendly for companies and versatile enough for every staff member.
An HMO might be your best option if you're trying to find a plan with a low premium. However, a PPO plan offers extra versatility if you require more control over your health care. That's why researching these strategies carefully, including their pros, cons, and typical expenses, is the very best very first step you can take previously making a choice.

Latest Posts

Choosing New Advantage Plans
Securing Coverage to Support Families

Comparing 2026 Term Life Insurance Premiums for Families